Slab Leak Insurance Coverage: What’s Usually Covered
Insurance and slab leaks get confusing fast. Here’s the plain version — and what to ask first.
Slab Leak Insurance Coverage: Quick Answers
The short version of this guide to slab leak insurance coverage:
- What Does Slab Leak Insurance Coverage Usually Pay For? Slab leak insurance coverage trips up most owners. Plans often treat the leak and harm apart.
- Why Is “Fast vs Slow” the Key? Firms draw a hard line here. Fast means all at once. Slow means drip by drip.
- What Does “Fast and by Chance” Mean? It means harm no one saw near. A pipe that bursts at night. A joint that fails with no warn.
Keep reading for the full guide to slab leak insurance coverage.
What Does Slab Leak Insurance Coverage Usually Pay For?
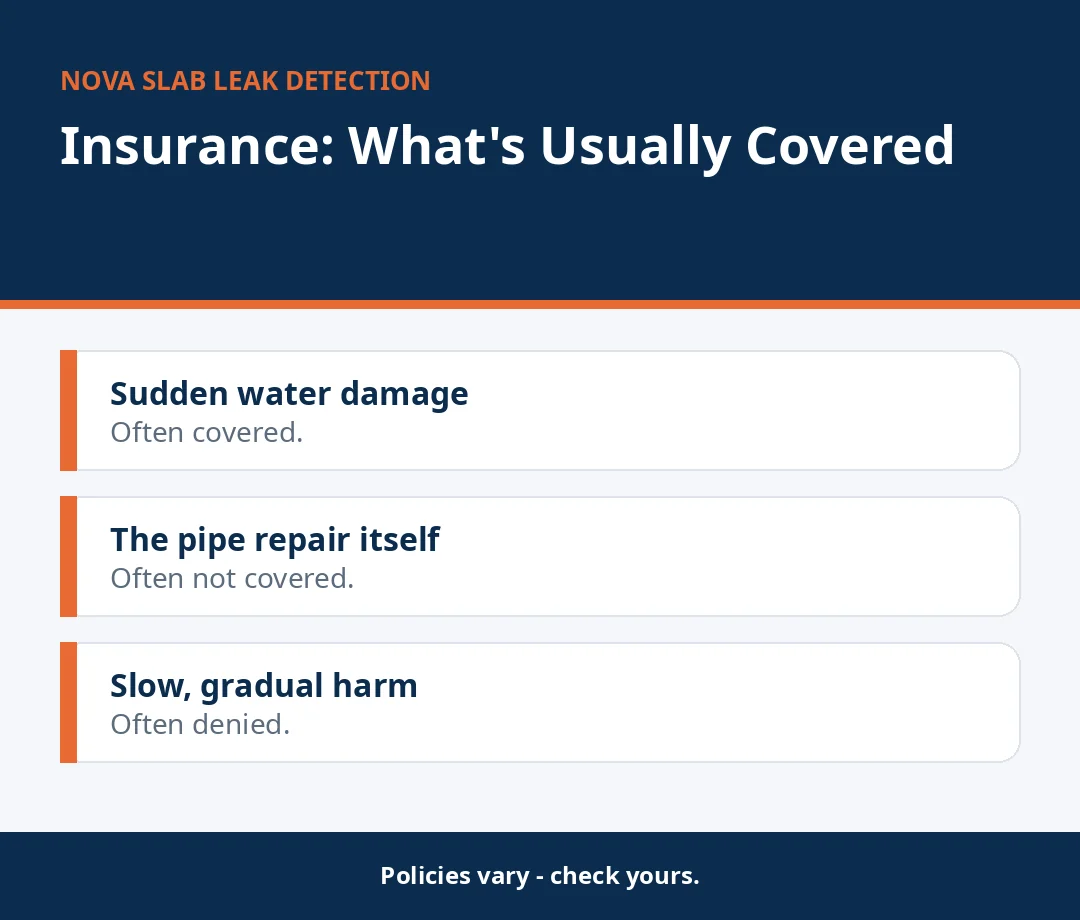
Slab leak insurance coverage trips up most owners. Plans often treat the leak and harm apart. The usual rule: fast harm may be paid, slow leaks often are not. Read your plan. Talk to your agent. We write down all we find.
Note: this is just facts, not advice. Plans differ by firm and state. Your agent knows your terms best.
Why Is “Fast vs Slow” the Key?
Firms draw a hard line here. Fast means all at once. Slow means drip by drip. Most plans pay for fast events, not slow wear. A burst pipe is fast. A year-long seep is slow.
Slab leaks sit in the gray zone. That gray gets claims denied. Know the terms before you file. Act fast when you see signs.
What Does “Fast and by Chance” Mean?
It means harm no one saw near. A pipe that bursts at night. A joint that fails with no warn. Firms want clear dates. They ask when you first saw signs.
Can a slow slab leak count as fast? At times. If it hit you all at once, say so. Dates count a lot. Keep notes from day one.
Why Do Dates Count So Much?
Dates prove your case. They show you acted fast. They fight claims of neglect. Write down each sign. Save each bill too.
What About the Harm the Water Did?
Here is what most miss. The pipe fix is often not paid. But the harm from water may be. Think dead floors and wet walls. Think warped wood.
In plain terms: lots of plans won’t pay for the pipe. Lots will pay to fix what water hurt. Read your own words with care. Ask your agent to make it clear.
| What happened | Often paid? |
|---|---|
| Sudden pipe burst | Often yes |
| Harm from burst water | Often yes |
| Slow seep, many months | Often no |
| Plain wear and tear | As a rule, no |
| Mold from fast leak | At times, caps set |
When Do Firms Say No?
Neglect tops the list. Firms want basic care. A leak you let run looks like neglect. Long seep looks like wear.
Will a wait hurt my claim? Often yes. Late word hints you could have stopped it. Tell them soon once you think leak. Write down each step.
What Counts as Neglect?
They mean you knew and sat still. Signs you brushed off. Bills you let climb. Fix fast and you look keen, not slack.
Who Gets the Last Word?
Your firm does, per your plan. A rep reads your claim. They read terms word by word. Gray bits get fought out.
You can fight a no. Ask what clause they used. Get it in print. Good notes win lots of fights. Big sums may need a pro on your side.
How Should You Track a Suspected Leak?
Start a file this week. Snap each wet spot. Date each first sign. Keep bills that show spikes. Log each call you make.
We aid with this. Our techs note what we find. Spots, reads, and dates go in. Strong notes aid any claim. Keep it all in one place.
What Should You Ask Your Agent?
Ask before you need it. Does my plan pay for slab harm? What are my mold caps? What do I pay first? How fast must I tell you?
Call the firm or us first? Stop harm first. Shut water if you must. Then call both of us. They want quick word, not best order.
How Do We Aid With Forms?
We find the leak and fix it. You get a plain typed note. It lists what we saw and did. Most hand it to their rep.
Detection is $150–$500. That is per national estimates as of 2026. Fix costs shift by type. Our work has our guarantee. If it isn’t right, call us. We’ll make it right. Questions? Call (833) 542-3027. We are here 24/7.
Want the full signs list? See slab leak detection. Track harm by week in our water damage timeline guide. More plumbing problem guides live here too.
What Records Should You Keep From Day One?
Start a leak file at once. Date each photo you take. Save bills that show jumps. Log each call with names. Keep our typed report. Store receipts for all fixes. Insurers love paper trails. Gaps in records hurt claims. A full file speeds payouts. Update it till the claim closes.
Digital copies back up paper. Email photos to yourself. Cloud files can’t burn or flood. Share the file with your agent early. Early sharing builds trust. Note the weather on big leak days. Note who you spoke with. Small facts win big fights. Good records turn fights into payouts.
Slab Leak Insurance Coverage: Frequently Asked Questions
Homeowners often ask us these questions about slab leak insurance coverage. Each answer is short, and the full detail on slab leak insurance coverage is in the sections above.
Related Slab Leak Problems
More guides related to slab leak insurance coverage:
- Slab Leak New Construction: New homes can leak too. Here’s why it happens and how we fix it fast.
- Slab Leak Radon Risk: A leak doesn’t make radon. But cracks can let it in. Here’s the calm truth.
- Slab Leak Renting Landlord: Renting with a slab leak? Here’s who usually pays and what to do first.
- All slab leak problems: Every warning sign, cause and risk in one place.
- Slab Leak Detection: How we find a leak under concrete without breaking it.
The EPA estimates the average household’s leaks can waste more than 9,300 gallons of water a year (EPA WaterSense), which is why slab leak insurance coverage is worth acting on early.
Slab Leak Insurance Coverage: Talk to Nova Today
Call any time, day or night. Tell us your ZIP code and what you are noticing, and we will book your visit. Mention slab leak insurance coverage when you call so we bring the right equipment.