What Should I Know Before Filing a Slab Leak Insurance Claim?
Filing a slab leak insurance claim means telling your insurer about water damage from a hidden pipe leak, then backing it up with proof. Call your insurer as soon as you find the leak, and send photos, dates, and our written detection report. Fast, clear records give your claim the best chance.
Why does speed matter? Water keeps moving under your slab. More harm can mean more cost. The EPA says to dry wet areas within 24 to 48 hours to hold back mold. So take photos first, then act fast to stop the water.
Will my insurer pay for the pipe repair itself? Often, no. Many plans pay for the water damage from a sudden leak, not for the bad pipe. Read your plan or ask your agent. Rules vary by plan and state.
Should I fix things before the adjuster comes? Stop active leaks and dry the area. But do not tear out floors or walls until you have photos and your insurer says it is okay. Keep the damage as you found it.
Who takes part in the claim? You, your insurer, the adjuster who checks the damage, and our technicians who find the leak and write the report you can share.
What Are the Steps to File a Slab Leak Insurance Claim?
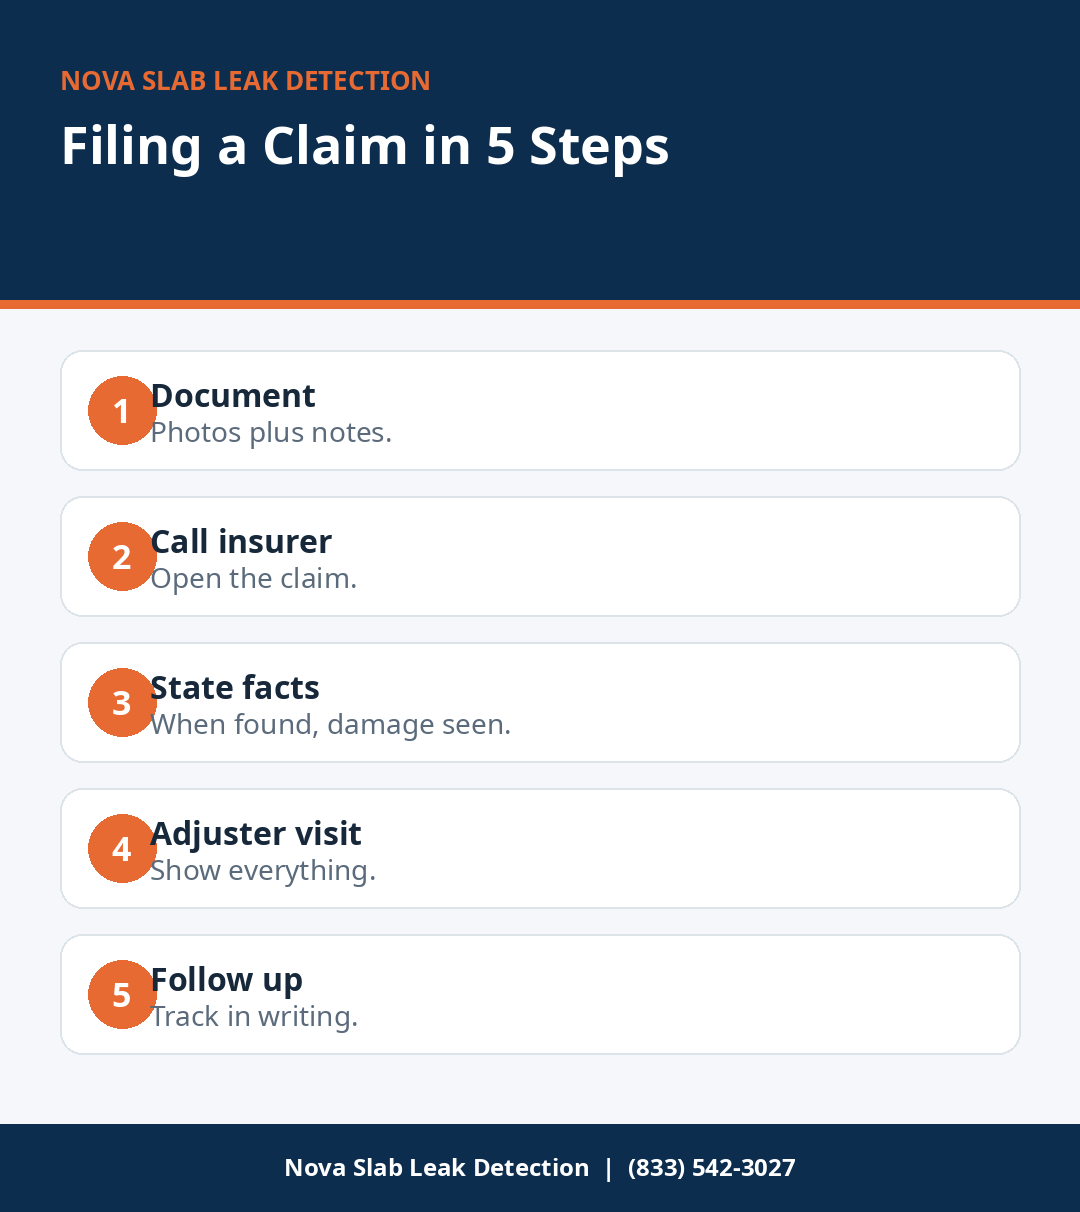
Follow these five steps in order. For more depth, see our insurance claims guide.
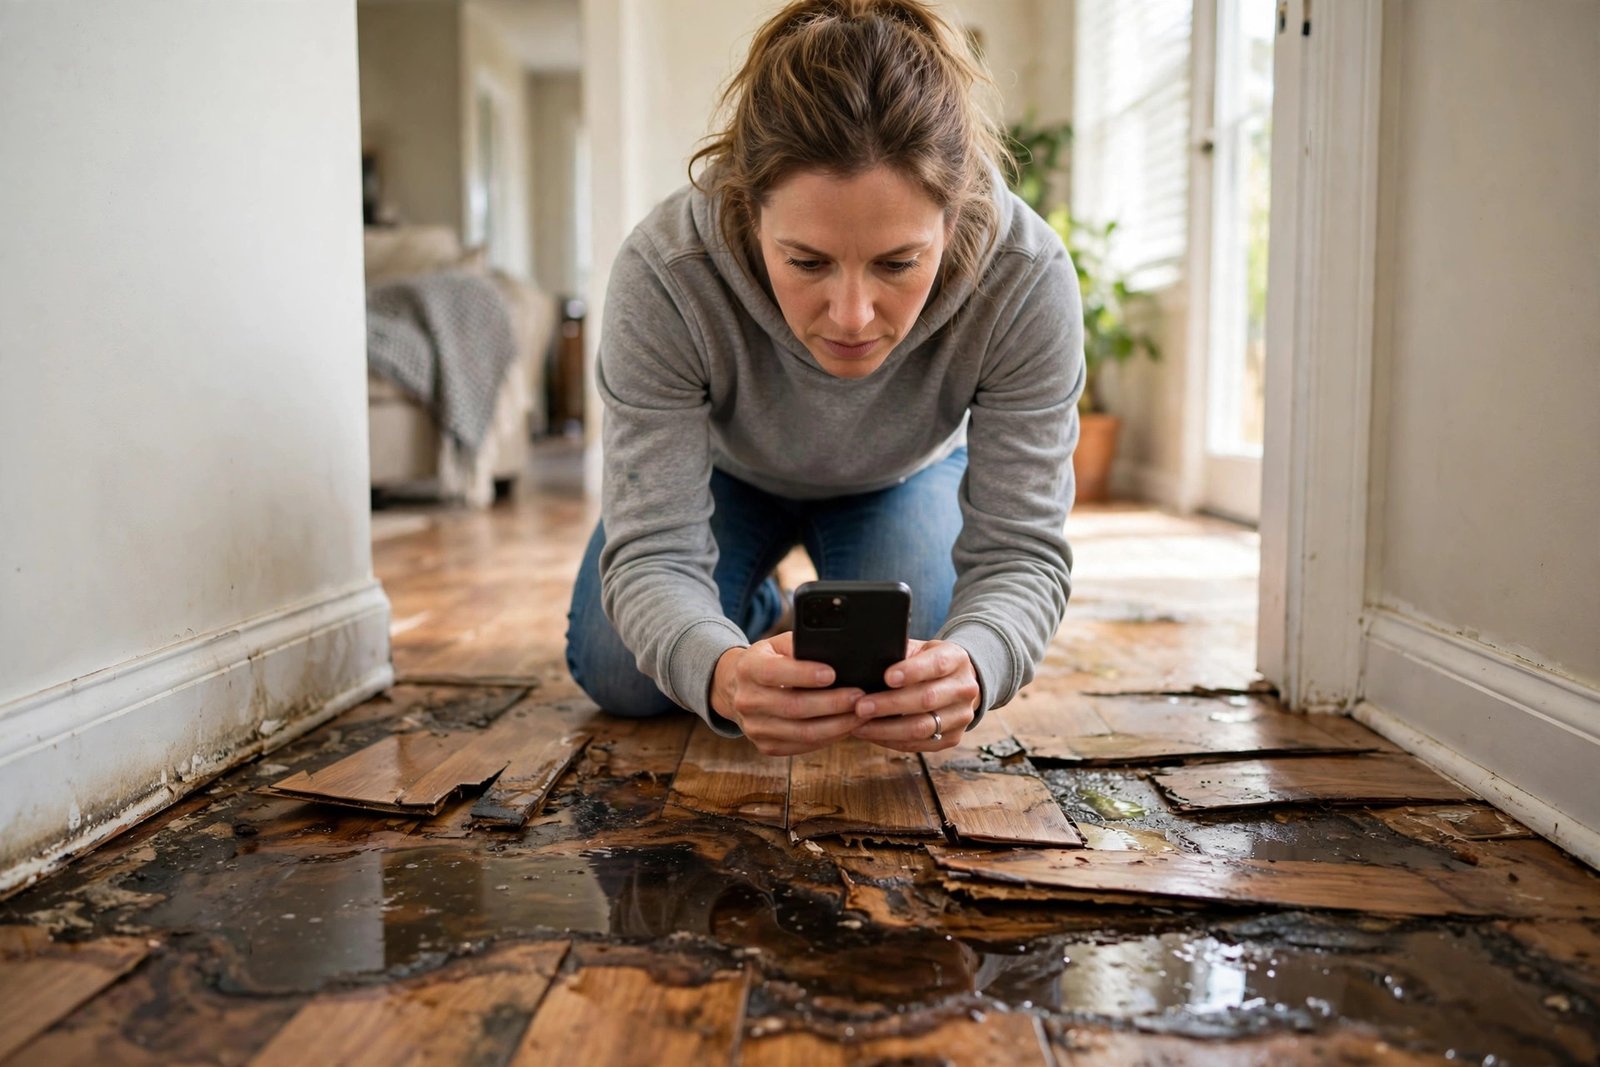
- Document the leak first. Write down the date you first saw signs. Take wide and close-up photos of wet spots, stains, and cracks. Save high water bills. Then call us. Our detection visit takes one to three hours and pinpoints the leak within about one to three feet. You get a written report with the leak spot, test results, and the date.
- Call your insurer right away. Use the claims number on your policy. Give your name, policy number, and the date you found the damage. Ask what proof they need and how to send it.
- Say what you know, and skip guesses. State the facts you saw. Do not guess the cause. Do not say how long it has been leaking if you do not know.
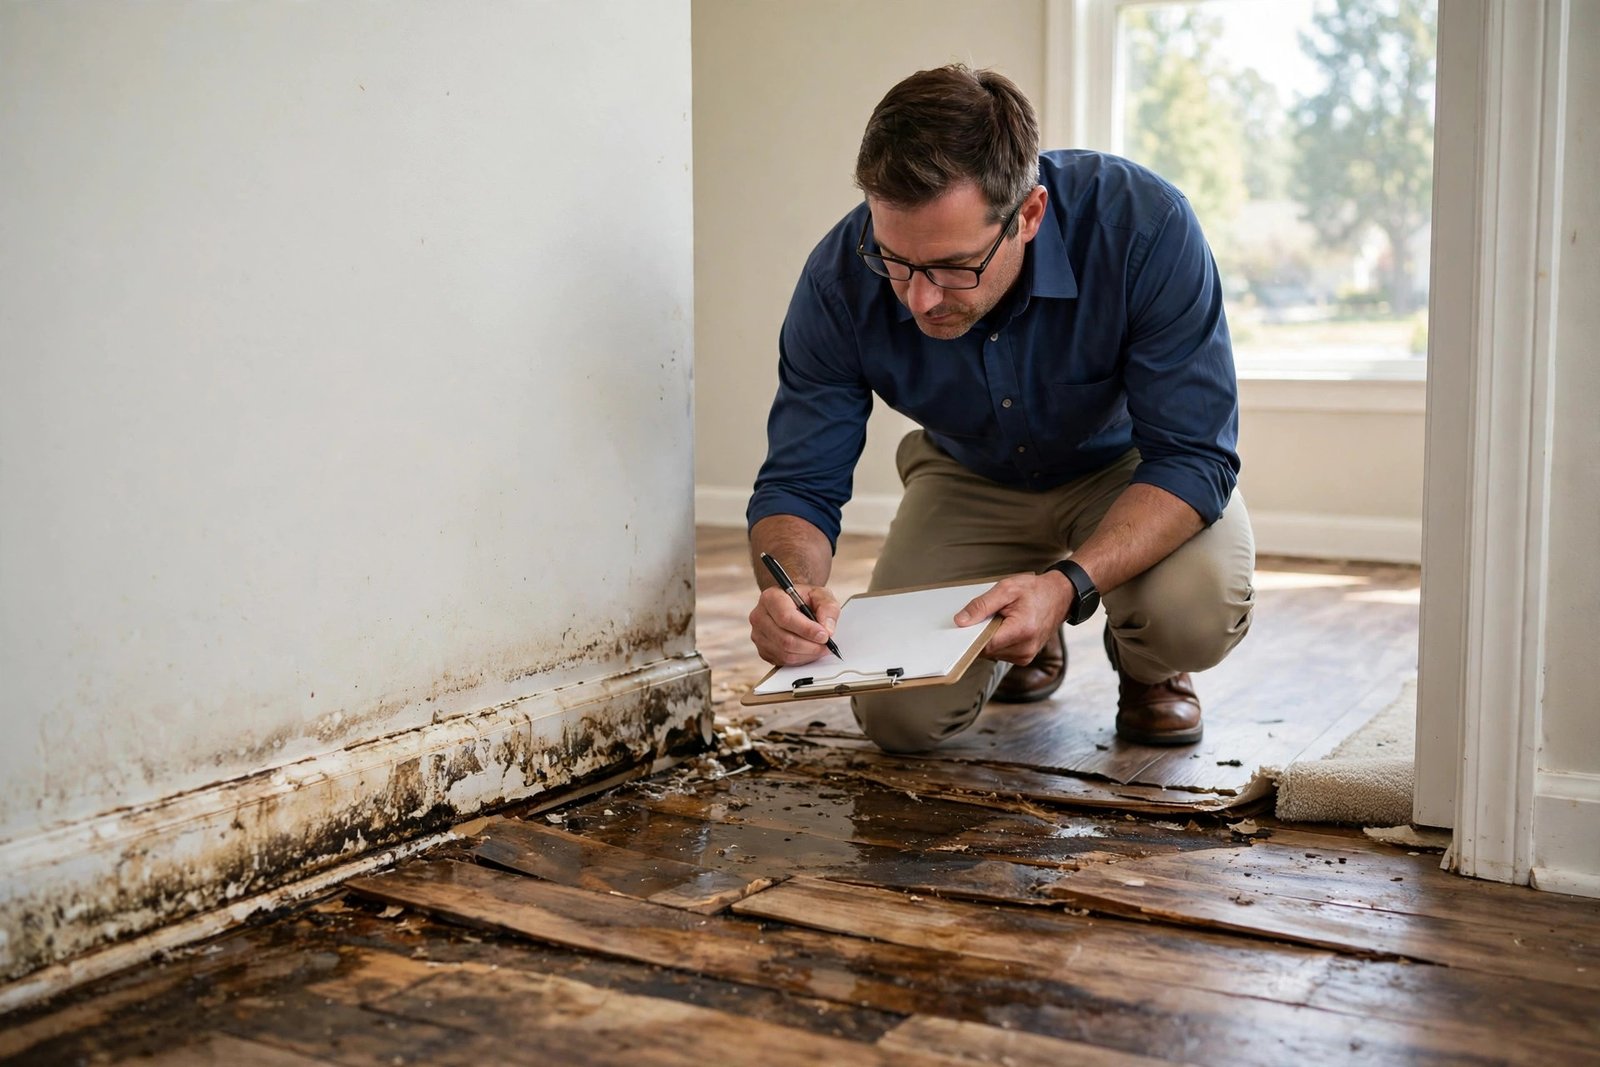
- Get ready for the adjuster visit. Keep the damage as you found it. Put your photos, dates, bills, and our report in one folder. Be home if you can. Walk the adjuster through what you saw, step by step.
- Keep every receipt. Save bills for detection, drying, repairs, and any hotel stay if you had to leave home. Note the date and what each bill was for. You may need them to get paid.
What Should I Say — and Not Say — to My Insurer?
The right words keep your claim clean. Stick to facts, not guesses.
| Say this | Do not say |
|---|---|
| “I found a wet spot on [date].” | “It has been leaking for months.” |
| “Our technician found the leak here.” | “I think the pipe burst because of age.” |
| “I dried the area to stop more harm.” | “I tore up the floor before I called.” |
| “Here is my written detection report.” | “Just trust me, it is bad.” |
The FTC urges home-repair buyers to get key facts in writing. The same rule helps here: dates, photos, and our report speak louder than words.
How Do Our Technicians Help With Your Claim?
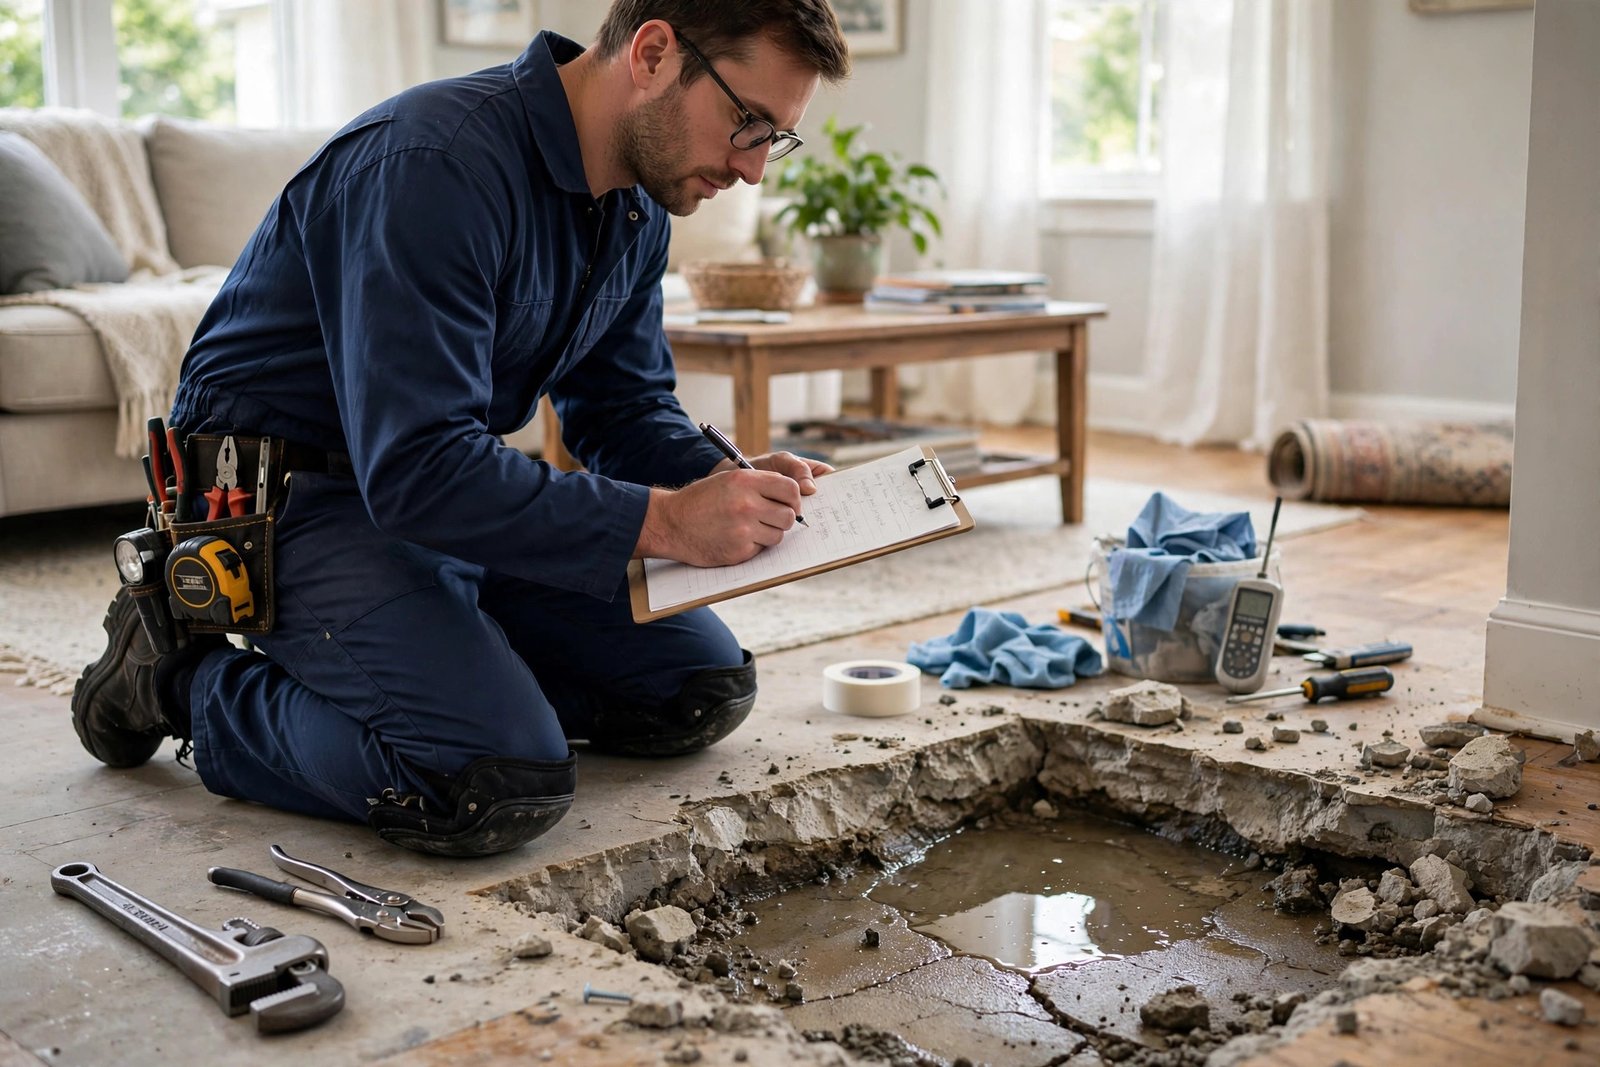
Our own technicians do the detection work, and they give you proof you can send to your insurer. Your report shows the leak spot, the test results, and the date of the visit. We list the repair options and the cost range for each, marked as national estimates as of 2026. A detection visit runs $150–$500 as national estimates as of 2026.
We serve homes in all 50 states and DC. You can reach us at (833) 542-3027. We are open 24/7, and the phone is the only way to reach us. To learn what plans often pay for, read our page on slab leak insurance coverage.
FAQs
Will insurance pay for slab leak detection?
Sometimes. Some plans pay for the search when it leads to a covered loss. Ask your agent first. Our written report helps either way.
What if my claim is denied?
Ask for the denial in writing and read the reason. You can appeal or ask for a second look. Plans vary, so check your own policy.
Can I pick my own repair company?
Most plans let you choose. Our own technicians do the work, with no hand-offs. Call (833) 542-3027 any time, day or night.
Could filing a claim raise my rates?
It can. Ask your agent before you file. Weigh the repair cost against your deductible first.
What if I rent my home?
Tell your landlord right away. The owner’s plan often covers the building. Rules vary by state, so check local law.
How long does a claim take?
Small claims can take days. Big ones can take weeks. Fast records and quick replies keep things moving. See all our FAQs for more help.